Inviting clients to football has tax consequences
by María Calle
Inviting clients to a football match, a game of golf, or a business dinner is a common way to build commercial relationships, and one that companies pursue as a matter of course. Spain's Supreme Court has nevertheless confirmed that, however clear and legitimate the commercial purpose behind these invitations may be, the value-added tax (VAT) paid on this kind of client entertainment cannot be deducted under Spanish tax law.
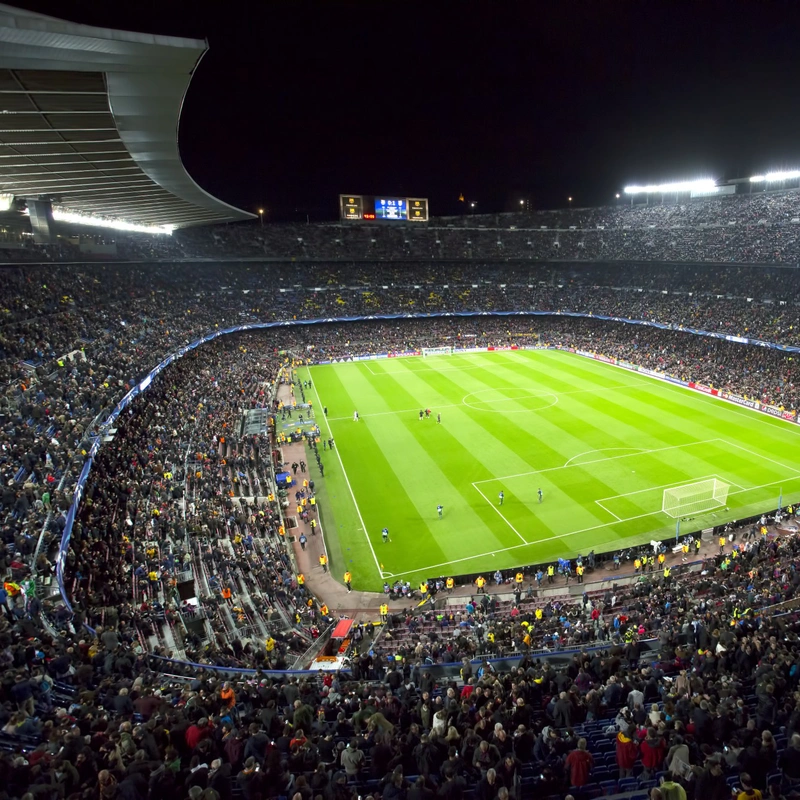
The dispute behind this doctrine originated in expenses incurred by Randstad España for tickets to Real Madrid and FC Barcelona matches, as well as a golf day, offered to employees of client and prospective client companies with the aim of strengthening commercial relationships and facilitating future business. The company argued that these costs were directly linked to its economic activity. The case eventually reached the Supreme Court, which referred a preliminary question to the Court of Justice of the European Union (CJEU) on whether the Spanish rule was compatible with EU law.
Article 96 of the Spanish VAT Act explicitly excludes from the right to deduction VAT charged on goods and services intended for “client entertainment”. In the STS 889/2026 and STS 924/2026 rulings issued in July 2026, the Supreme Court confirmed that this exclusion remains fully in force. The court made clear that demonstrating an invitation pursues a legitimate business objective does not automatically transform the related expense into a VAT-deductible one.
The CJEU, in its 12 March 2026 ruling in the Randstad España case (C-515/24), validated the Spanish exclusion on the basis of the so-called “standstill clause” contained in Article 176 of Directive 2006/112/EC. That clause allows member states to maintain deduction restrictions that existed before their accession to the common VAT system.
The practical lesson is straightforward: for tax purposes, a business expense and a VAT-deductible expense are not equivalent concepts. Companies running client loyalty, representation, or public relations policies should therefore assess the VAT and corporate income tax treatment of these expenses separately. Client entertainment costs may still qualify as deductible under Article 15.e of the Corporate Income Tax Act, even though the related VAT cannot be recovered. A ticket to a football match can be an effective commercial tool, but, following the Supreme Court's recent rulings, using it as client entertainment carries a clear tax consequence: the VAT paid on the ticket falls outside the right to deduction.
María Calle is an economist and studied Business Administration at the Universidad San Pablo CEU in Madrid. She has more than 10 years of experience in accounting and tax consulting for small and medium-sized businesses and self-employed professionals, as well as experience in customer service in the banking and real estate sectors. She joined Ruiz Ballesteros in November 2019.